How to optimise your SME payment infrastructure for Australia peak sales season
23 October 2026
12 min read
KPay Editorial Team
Making the complex sides of financial management, business operations and digital transformation simple. We share practical tips and local stories to help you run your business smarter and grow faster.
Key takeaways:
Payment infrastructure is a network of different payment systems: Online payment gateways, terminals, issuing banks, card networks and acquiring banks move funds from a customer's payment method into a business's account across three stages: authorisation, clearing and settlement.
APAC has the highest cart abandonment rate globally: Measured at 81.53%, compared with a 77.55% global average. Payment friction is a leading cause.
Merchants need to prepare for high customer volume during peak periods: Load-testing your systems, auditing your payment infrastructure in advance and reviewing your merchant account will help you catch weak points before they turn into lost sales, delayed settlement or a frozen account mid-sale.
Choosing a reliable payment gateway for online businesses: SMEs (small-medium enterprises) using established gateway providers typically don't need to load-test the gateway itself, since these platforms operate at a scale beyond a single SME's peak traffic. The priority is testing your own website and checkout integration.
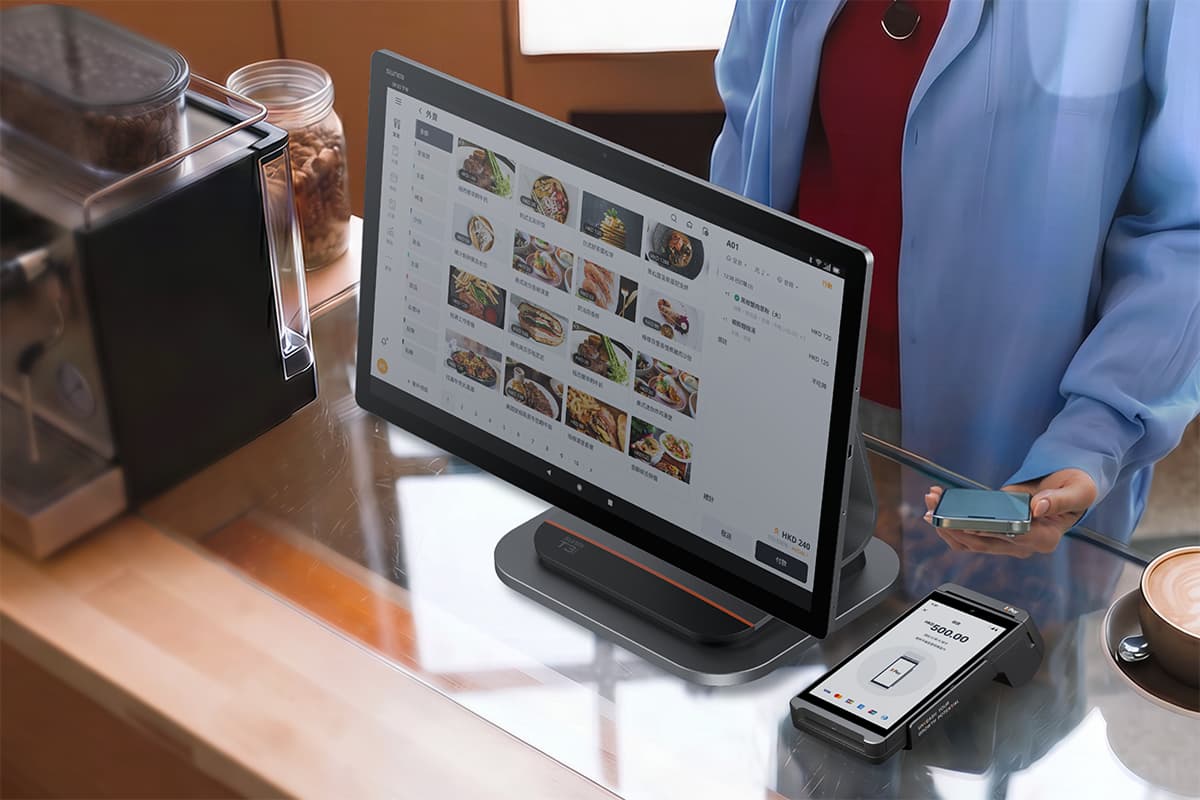
Setting up safety nets for in-person payments: Terminal failures during peak footfall are most commonly caused by a lost network connection, not hardware failure. A backup connection or alternative payment method is essential for physical retail.
It's the opening night of a big sale, and your customer adds two items to their cart. They head to checkout, choose their payment method and go to finalise the sale. The screen loads for several seconds, and then an error message appears. The payment can't go through.
Behind the scenes, transaction volume has spiked well beyond what your payment infrastructure was built to handle. A sale has just been lost to an unanticipated delay, whether the customer was checking out online or standing at the counter.
In Australia, sales like Black Friday, Cyber Monday, Click Frenzy, End-of-Financial-Year (EOFY) and AfterPay Day, and events like Christmas and Boxing Day sales make or break an SME's year. A strong peak season can carry months of revenue in a single week. A bad one leaves refund requests, overstretched teams and revenue losses that outlast the sale itself.
Learn how to optimise your payment infrastructure to keep more of that demand from slipping away.
What is a payment infrastructure?
For an SME, your payment infrastructure is your entire payment acceptance setup:
The payment methods you offer customers.
The banking relationships (your acquiring bank and merchant account) that receive and settle those funds.
It's every system that stands between your customer paying and you receiving the funds. Australian customers use a wide range of payment methods, but cards dominate. The Reserve Bank of Australia's 2025 Consumer Payments Survey found that cards made up 73% of consumer payments. Digital wallets are forecast to rise from 21% of transaction value in 2025 to 32% by 2030. An SME that's selling locally needs to support more than one channel to capture the full range of how customers want to pay.
How does a payment infrastructure work?
At its core, your payment infrastructure connects three things every time a transaction happens:
the payment method your customer uses,
the parties who verify and move the funds, and
your merchant account, where the funds end up.
Each transaction moves through three broad stages: authorisation, clearing and settlement. How those stages play out depends on the payment method.
Some payment methods, such as cards, route through several intermediaries:
Authorisation: The issuing bank confirms the card's validity and the availability of funds.
Clearing: The transaction is reconciled between your customer's issuing bank and your acquiring bank. Processing fees are calculated and deducted before the net amount is settled into your account.
Settlement: Funds are transferred into your merchant account, normally within one to three business days.
To the customer, whether paying online or at a terminal, this looks instant. Behind the scenes, it passes through a short chain of parties:
Online payment gateway or EFTPOS machine: Used when the customer makes payment.
Issuing bank: The customer's bank, which issues their card and approves or declines the transaction.
Acquiring bank: Your business's bank, which provides the merchant account and receives the settled funds on your behalf.
Card network: The system (for example Visa, Mastercard or eftpos) that connects issuing and acquiring banks, routes the transaction and sets the rules and fees for using the network.
Other payment methods, such as BNPL and PayID, route through simpler paths:
Buy Now, Pay Later: The provider checks affordability, approves the purchase and pays you upfront, minus a fee. The customer repays the provider in instalments.
PayID: The customer enters the recipient's PayID in their banking app, their bank confirms the name, and the funds reach you near-instantly over the New Payments Platform (NPP), 24/7.
The result is the same either way, but the number of intermediaries, and therefore the fees and settlement speed, differs by method. This is why your payment infrastructure needs to support more than one processing path.
The costs of weak payment infrastructure during peak season
Peak season is when your payment infrastructure gets put to the test. Sudden surges push every part of it at once, whether that's contactless payments at the terminal, or card, Afterpay and PayID payments online. Any weak point that normal volume never touches, such as a slow gateway, an unsupported payment method or a settlement delay, gets exposed the moment demand spikes.
The hidden cost of checkout friction
Checkout friction causes real costs, including abandoned carts, failed retries and chargebacks. They trace back to a payment experience that felt complex and clunky, not to weaker demand. Research shows that 21% of customers abandon carts due to a complicated or lengthy checkout, a cost that's easy to overlook precisely because it never shows up as a single, obvious loss.
Weaker cash flow during peak sales periods
Infrastructure-driven delays tend to surface during peak season. They can leave confirmed sales stuck as unavailable funds, right when you need cash most for restocking, staffing or supplier payments.
Capacity-triggered risk holds
An unexpected spike in transaction volume can look like fraud to your acquirer, triggering a temporary hold on settlement. Without advance notice of expected peak volume, a legitimate sales surge gets flagged as a risk signal instead of growth.
The fix is simple: tell your payment service provider about expected volume before the sale, so your funds aren't withheld.
Settlement delays
A confirmed sale isn't the same as cash in hand. Between authorisation and settlement, funds sit in transit. During peak season, that gap widens as banks and processors work through higher volume across every merchant, not just yours.
Card settlement typically runs on business days, so sales made over Christmas, Boxing Day and New Year's Day may land later than usual. For an SME, this mismatch bites hardest right after a big sale, when suppliers expect payment and shelves need restocking. Plan for the gap with a short cash buffer or a clear view of your settlement timeline.
Common payment infrastructure failures during high-traffic sales events
Peak traffic tests every layer of the payment chain at once, and it's usually the same few points that give way first.
Payment gateway timeouts under load
Gateways time out when transaction volume exceeds what the integration was built to handle. Customers are left on a loading screen, unsure whether they've been charged. This is one of the most common and damaging failure points because it creates uncertainty at the exact moment a customer is ready to pay.
Issuing bank authorisation delays
Authorisation delays happen when the issuing bank's systems are strained by sale-day volume across many merchants, not just yours. There's little an individual SME can do to fix this directly.
However, adding payment methods such as digital wallets, BNPL, PayID or payment links can cushion the impact of a slow card network.
Payment terminal connection failures during peak traffic
A payment terminal is only as reliable as its connection, and busy periods are when that connection is most likely to drop. In a packed flagship store on Sydney's Pitt Street Mall, or at a stall in Melbourne's Queen Victoria Market on a Christmas weekend, an overloaded shared Wi-Fi router or a mobile terminal losing signal in a crowded space can knock out card and wallet payments all at once.
When this happens, transactions can't be authorised. Customers queue with no way to pay, and staff have no fallback unless a backup connection or offline mode is already in place.
Auditing your payment infrastructure before the sale
Reviewing your payment methods and merchant account against expected peak load shows whether your setup can handle several times your normal transaction volume. It also buys you time to fix problems before they become bottlenecks.
Confirming backup payment methods are available offline
If your primary terminal or connection fails, a fallback determines whether you keep serving customers or turn them away.
Check that staff can accept payment another way, whether that's a separate terminal on a different network or a backup such as PayID. A terminal with offline features keeps queues moving and staff focused on helping customers in-store.
Reviewing your merchant account setup
Your merchant account is where you can:
Check your current processing limit: Log into your merchant dashboard or contact your provider to confirm your monthly (and daily or per-transaction, if applicable) processing cap.
Estimate your expected peak-season volume: Compare last year's sale-period revenue, or your regular monthly volume multiplied by your expected spike, against that cap.
Request a limit increase in advance: If your estimate is close to or exceeds your cap, ask your provider to raise it before the sale, not during it.
Ask what happens if you exceed the limit: Some providers hold funds or flag the account automatically. Knowing this in advance means you won't be caught off guard.
Confirm your account's risk profile is up to date: A sudden, unexplained spike can look like fraud to your acquirer. Share your expected peak dates and volume ahead of time.
Load-testing checkout and payment flows for online shops
Before major events like Black Friday, Click Frenzy or Boxing Day sales, load-testing shows whether your checkout survives concurrent web traffic before real customers find out the hard way. Tools like k6, Apache JMeter or Loader.io can simulate shoppers browsing, adding to cart and checking out at the same time, even if you have no technical background.
For most SMEs, load-testing the payment gateway itself isn't necessary. Established providers are built to handle volumes far beyond a single merchant's peak traffic. Focus on stress-testing your own website and checkout integration.
When to load-test: At least three to four weeks before the sale goes live.
Provide a smooth online checkout with KPay Payment Gateway
KPay Payment Gateway gives online merchants a fast, secure, and flexible payment experience — removing the complexity often faced during integration and reducing the number of failed transactions. Here is how KPay's Payment Gateway can help businesses to focus on converting customers instead of fixing payment problems:
All major payment methods, one integration: After connecting the payment gateway to your website using our plug-in or API, you can start accepting payments via credit cards, debit cards, and a growing range of digital wallets and local payment methods.
Enterprise-grade security: KPay is ISO 27001 certified and PCI DSS Level 1 compliant, partners with HSBC, and holds operating licences in Hong Kong, Australia and Singapore.
Confirming PCI DSS compliance, encryption and tokenisation
Compliance and encryption checks protect customer data and your business from liability during the highest-risk week of the year. Confirm your PCI DSS compliance check is up to date, card data is encrypted in transit and tokenisation is in place, so raw card numbers are never stored or exposed.
How to build scalable and secure payment infrastructure for peak demand
Scalability and security go together. A system that can't handle high traffic is also more exposed to the fraud and errors that come with it. Add capacity where you need it and shore up weak points before volume peaks.
Offering multiple, optimised payment methods across every channel
Accepting cards, digital wallets, BNPL and PayID reduces the chance that one failed payment method costs you the sale. This matters online and in-store. A terminal that accepts only cards, or only one wallet, forces customers to queue elsewhere or abandon the purchase.
You can also cut card costs with dual-network debit cards. Least-cost routing sends contactless debit payments through whichever network (eftpos or Visa/Mastercard) is cheaper.
Accepts 12 major payment methods seamlessly on one portable device
No subscription fees, annual fees or terminal rental fees
Same-day settlement* gives you faster access to your takings.
Secure transactions and data points with industry-leading security standards, including PCI DSS, AICPA Soc 1 & 2, and ISO 27001.
24/7 customer support, every day of the year to ensure merchants get up and running quickly should any issues occur.
Access real-time sales reporting, peak hour analysis, and transaction reconciliation with KPay's Merchant App
With KPay Terminal Pro you can meet your customers' needs for speed, versatility of payment methods, and ensure secure transactions — all with one device.
Preventing overload with ample payment capacity
Queues form when transactions waiting to be processed outpace the payment stations available, whether that's checkout lanes online or terminals in-store. Keep enough capacity in reserve to prevent a bottleneck that customers give up on.
Online: A virtual queue at launch protects checkout from traffic surges.
in-store: Have enough payment devices and staff to prevent physical queues, and a POS system that processes transactions smoothly when footfall spikes.
Enabling real-time payments for faster confirmation
Real-time payments confirm transactions instantly instead of leaving customers on a pending status.
Online: PayID transfers, digital wallets and payment links offer near-instant confirmation. Faster verification reduces uncertainty and keeps checkout moving.
in-store: Devices that confirm payment and generate a receipt in seconds, rather than lagging under load.
Automating reconciliation and fulfilment around your payment infrastructure
Automating the manual parts of reconciliation keeps records accurate and problems visible, even as everything else moves faster than usual.
Connecting payment infrastructure to inventory and accounting systems in real time
Real-time connections between payment, inventory and accounting systems prevent the overselling and stock errors that follow a payment surge. Manual reconciliation that works on a normal day breaks down under sale-day volume.
Automating invoices, receipts and payment confirmations
Automated invoices and confirmations keep records accurate the moment a sale completes, with no manual entry afterwards. This matters most in peak season, when volume makes manual reconciliation impractical.
Using automation to flag payment issues in real time
Automated alerts on failed transactions, unusual fraud patterns or settlement delays let you act on problems as they happen, not after volume has dropped off. This is especially valuable for SMEs without dedicated finance staff to monitor transactions during a sale.
Final pre-sale checklist for payment infrastructure readiness
With the bigger fixes in place, the final stretch is about closing small gaps and confirming everything works together. Run through this checklist in the days before launch.
1. Run a live test transaction and confirm rollback plans
A live test transaction confirms your whole payment process works end to end, not just in isolated pieces. Pair it with a documented rollback plan so a last-minute issue doesn't become a prolonged outage.
2. Assign an owner to monitor uptime and payment success rates during peak hours
A named owner watching uptime and payment success rates can catch and escalate problems before they affect a meaningful share of transactions. Without one, early warning signs get missed until conversions have already dropped.
3. Freeze non-essential changes 48 hours before launch
A code freeze in the final 48 hours stops last-minute changes from introducing new failures in your highest-stakes window. Test and sign off any change to payment or checkout systems well before the sale begins.
FAQs
How far in advance should I test my payment infrastructure before peak season?
Start load-testing and auditing your payment stack at least three to four weeks before the sale. This usually leaves enough time to fix issues the testing reveals, rather than discovering them on launch day.
What's the single most common payment infrastructure failure during big sales?
Checkout and payment gateways buckling under concurrent load is the most common and typically the most costly failure, since it hits customers at the exact moment they're ready to buy. Prioritise load-testing and scaling this path above every other part of your infrastructure.
Get in touch with KPay to find out how our range of payment solutions can support your business this peak sales season.